How I Turned KSh 5,000 Into a Monthly AI-Powered Income Stream in Kenya
How KSh 5,000/month consistently invested with AI guidance builds a real monthly income stream in Kenya
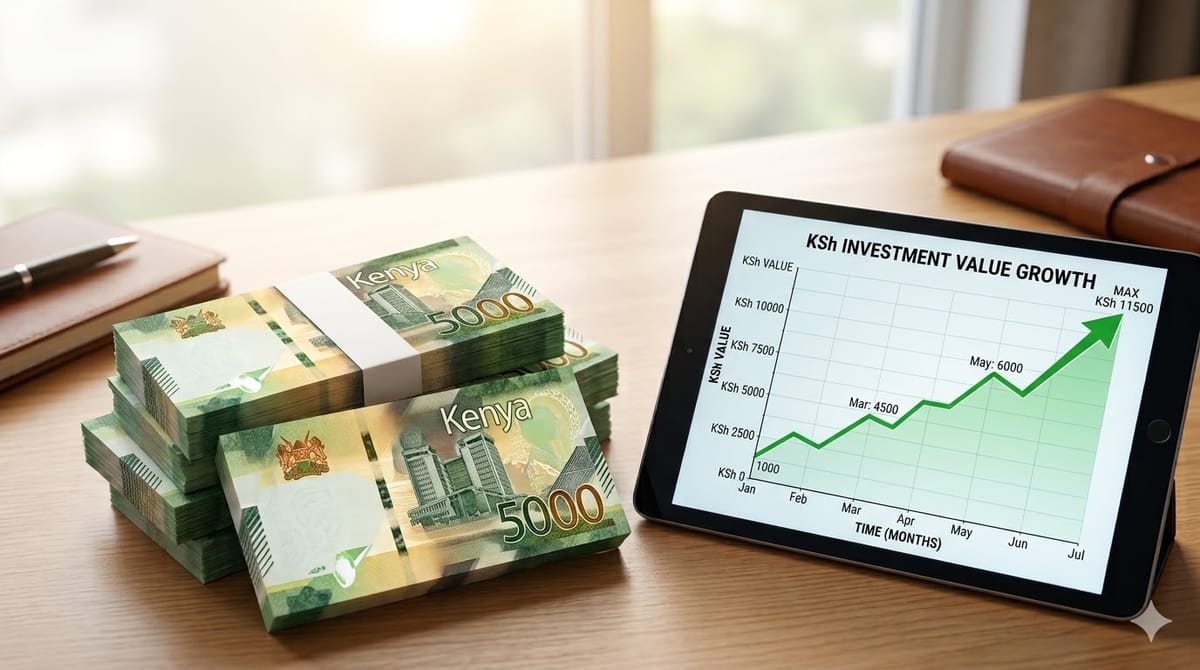
The most common reason Kenyans give for not investing is not what you might expect. It is not 'I don't trust the market' or 'I don't know where to start.' It is simpler and more honest than either of those:
'I don't have enough.'
KSh 5,000 does not feel like enough. It feels like a month's transport budget, or two weeks of groceries, or a fraction of one emergency. It does not feel like the beginning of a meaningful income stream.
It is, though. That is what this post is about not theory, not inspiration, but the actual mathematics of what KSh 5,000 per month does when it is consistently invested with intention, in the right vehicles, using AI to make better decisions than you would make alone.
By the end, you will see exactly what your money does month by month, year by year and understand why the amount you start with matters far less than the date you start.
📊 THE NUMBERS: KSh 5,000 invested monthly in a vehicle returning 12% annually generates approximately KSh 634 per month in returns by the end of Year 1. By end of Year 3: KSh 2,150/month. By Year 5: KSh 4,110/month, nearly a full month of contribution, returned as passive income every single month, without touching the principal.
1. What 'Monthly Income Stream' Actually Means
Before the numbers, a definition because 'passive income' is one of the most misused phrases in personal finance content.
A monthly income stream from investing does not mean you get a fixed payment deposited to your M-Pesa on the first of every month. Different investment types generate returns in different ways and on different schedules. Here is what 'income stream' actually looks like across the Kenyan investment landscape:
Daily - money market fund interest
MMFs calculate and credit interest to your account every single day. You do not see a separate payment, the balance just grows slightly each day. At KSh 5,000 invested at 12% annually, your daily interest is approximately KSh 1.64. Small individually, but it compounds continuously.
Quarterly/at maturity - treasury bill interest
When a 91-day T-bill matures, the face value plus interest is credited to your DhowCSD account. On a KSh 50,000 bill at 15% annual yield, that is approximately KSh 1,849 paid every 91 days roughly KSh 616 per month on average.
Annually - NSE dividends and SACCO dividends
Most NSE companies pay dividends once or twice per year. SACCOs typically pay annual dividends on member deposits. These are lump-sum payments that you receive on a schedule, not monthly trickles. For income stream purposes, you mentally divide the annual payment by 12 to get the monthly equivalent.
Variable - affiliate commissions and digital products
If you run a blog, YouTube channel, or social media presence about personal finance like this one, affiliate commissions and digital product sales generate income that varies month to month based on traffic and conversions. This is not a traditional investment return, but it is increasingly part of the income stack for Kenyan content creators who monetise their financial knowledge.
✅ KEY TAKEAWAY: An income stream from investing is not one payment arriving on one day. It is multiple flows of different sizes, frequencies, and types, all generated by money you invested previously. The goal is to build enough of these flows that together they become meaningful relative to your monthly needs.
2. The Growth of KSh 5,000/Month - Month by Month
This table shows what happens to KSh 5,000 invested monthly in a money market fund or similar vehicle returning 12% annually with returns reinvested, not withdrawn.
| Month | Monthly investment | Cumulative invested | Portfolio value (12% p.a.) | Monthly return generated |
| Month 1 | KSh 5,000 | KSh 5,000 | KSh 5,050 | KSh 50 |
| Month 6 | KSh 5,000 | KSh 30,000 | KSh 30,927 | KSh 309 |
| Month 12 | KSh 5,000 | KSh 60,000 | KSh 63,412 | KSh 634 |
| Month 24 | KSh 5,000 | KSh 120,000 | KSh 135,640 | KSh 1,356 |
| Month 36 | KSh 5,000 | KSh 180,000 | KSh 215,000 | KSh 2,150 |
| Month 48 | KSh 5,000 | KSh 240,000 | KSh 306,000 | KSh 3,060 |
| Month 60 | KSh 5,000 | KSh 300,000 | KSh 411,000 | KSh 4,110 |
Read that last row carefully. By month 60, five years of KSh 5,000 monthly investments, you have put in KSh 300,000 in total contributions. Your portfolio has grown to approximately KSh 411,000 because of compounding. And it is now generating approximately KSh 4,110 per month in returns which is 82% of what you are contributing, earned passively.
At some point beyond this table, the monthly returns from your existing portfolio exceed your monthly contributions. That is the crossover point i.e the moment when your money starts contributing more than you do. It does not require a large salary. It requires time and consistency.
⚠️ IMPORTANT: These projections assume a consistent 12% annual return. Actual money market fund returns fluctuate with Kenya's interest rate environment. When the CBK cuts rates, MMF returns typically decline. The figures above are illustrative using a reasonable historical average, not a guarantee of any specific outcome.
3. Building Multiple Income Streams - The Full Stack

KSh 5,000/month into a single money market fund is an excellent start. But as your capital grows, diversifying across different income-generating vehicles creates a more resilient and faster-growing total income stream. Here is the full picture of what a Kenyan investor's income stack can look like:
| Income stream | How it works | Monthly income at KSh 200K invested | Time to set up | AI role |
| MMF daily interest | Earns 12% p.a. compounded daily on balance | ~KSh 2,000 (accrued, not paid monthly) | 20-30 min | Chose fund, calculated returns |
| T-bill interest | 91-day bills at 15% p.a. — paid at maturity | ~KSh 2,500 per KSh 200K bill at maturity | 1-2 days | Explained auction process |
| NSE dividends | Quarterly/annual dividend from shareholding | KSh 800-1,500 (depends on stock/season) | Account: 30 min | Researched dividend history |
| SACCO dividends | Annual dividend on member deposits (~12%) | ~KSh 2,000 (paid annually, not monthly) | Join: 1 day | Explained SACCO mechanics |
| Affiliate commissions | Earn % when audience signs up via your links | KSh 0-5,000+ (grows with audience) | Apply once live | Drafted content, wrote prompts |
| Digital product sales | Sell an AI prompt pack or guide on Gumroad | KSh 0-8,000+ (scales with traffic) | 1-2 days to build | Built the product itself |
The two rows at the bottom affiliate commissions and digital product sales are the ones that AI tools make newly accessible for ordinary Kenyan investors. This blog is itself an example. By sharing what you learn about AI and investing, you create content that generates affiliate commissions when readers sign up for tools you recommend, and digital product sales when readers buy a guide or prompt pack you have created.
This is not a get-rich-quick angle. Affiliate and product income takes time to build. But it compounds on the back of the financial knowledge you are already building which makes it genuinely aligned with the rest of your income stack in a way that most side income ideas are not.
4. How AI Helped Me Build This - The Specific Prompts
At each stage of building an income stream from investing, free AI tools answered questions that would otherwise have required either expensive professional advice or months of trial and error.
When I was starting with just KSh 5,000/month:
"I can invest KSh 5,000 per month in Kenya. I want to build toward generating meaningful passive income from investing. Given this amount, what is the best single Kenyan investment vehicle to start with, and why? Show me what my balance and monthly returns will look like at month 6, 12, 24, and 36 if I invest consistently and reinvest all returns."
When my balance grew toward KSh 50,000:
"My money market fund balance has reached KSh 52,000. I earn KSh [salary] monthly and can now invest KSh [amount] per month. Please advise: should I keep everything in the MMF or begin adding treasury bills through DhowCSD now that I can meet the minimum? If I split how should I split, and what does my blended return look like? Show the maths."
When I began building the digital income layer:
"I run a personal finance blog in Kenya focused on AI tools for investing. I want to add affiliate income to my blog as a secondary income stream. Which specific affiliate programs are available to Kenyan content creators in the personal finance and AI tools space? For each one, what is the commission structure, minimum payout, and payment method and do any accept M-Pesa or bank transfer to Kenya?"
For quarterly portfolio review:
"Here are my current investment balances in Kenya as of [month]: MMF KSh [balance], T-bills KSh [face value], NSE stocks (market value) KSh [value], SACCO KSh [balance]. My monthly investment amount is KSh [amount]. Please calculate: my current blended annual return across all instruments, my total monthly income from all investment streams combined, and whether I am on track to reach KSh [goal] by [date]. What should I change, if anything?"
5. The Three Stages of Building Your Income Stream
Stage 1: Foundation (KSh 0 to KSh 100,000 invested)
At this stage, the monthly income from your investments is small, typically KSh 500 to KSh 1,200 per month. Do not expect to feel the impact of this income on your monthly finances yet. The purpose of Stage 1 is not the income, it is the habit, the account, and the compounding foundation.
Your entire focus here is: invest consistently every month, reinvest every return, do not withdraw anything. The MMF is the right vehicle for most people at this stage it is accessible, liquid, and earning materially more than a savings account.
Stage 2: Growth (KSh 100,000 to KSh 500,000 invested)
This is where the income stream starts to become noticeable. Monthly returns from all investments combined will typically range from KSh 1,500 to KSh 6,000 depending on your allocation. You will begin to see dividends arrive from your NSE holdings. T-bill maturities will feel meaningful. The SACCO annual dividend will be a welcome addition.
At this stage, the key decision is whether to continue reinvesting all returns or to begin withdrawing a portion. The answer depends entirely on your goals, if you are building toward a specific KSh target, keep reinvesting. If you are building toward a specific monthly income floor, you can begin withdrawing a portion once you are comfortably above that level.
Stage 3: Momentum (KSh 500,000+ invested)
At this level, the monthly return from your investment portfolio begins to approach or exceed your monthly contribution. This is the compounding momentum phase where the portfolio itself becomes a meaningful contributor to your financial goals, not just your monthly savings habit.
For most Kenyans reaching Stage 3, the conversation with AI tools shifts from 'how do I grow this' to 'how do I manage and protect this.' Rebalancing, tax efficiency, SACCO loan strategies, and long-term NSE portfolio allocation become the primary questions.
💡 AI PROMPT: "I have reached KSh [amount] invested across MMF, T-bills, NSE stocks, and a SACCO in Kenya. My monthly income from all investment streams combined is approximately KSh [amount]. I am now thinking about the next stage whether should I continue reinvesting everything, begin withdrawing some income, or rebalance my allocation? My age is [age] and my primary financial goal at this stage is [goal]. Please help me think through this decision with specific recommendations and the reasoning behind them."
6. The Honest Timeline - When Will It Feel Real?
This is the most important section of this post because most people who start building investment income streams stop before they feel meaningful. Understanding the timeline removes that temptation.
Month 1-3: Invisible
Your monthly return is between KSh 50 and KSh 200. You will not notice it. This is normal and expected. The only purpose of these months is establishing the habit and the account. Keep going.
Month 6-12: Encouraging
Monthly returns from your MMF will be KSh 300-700. You might start to see this as your phone's data budget, or a portion of your transport costs. The psychological shift from 'invisible' to 'something' is significant, this is when most people who have stayed consistent start to feel genuinely motivated.
Year 2: Meaningful
Monthly returns across your growing portfolio including first T-bill maturities and possibly first NSE dividends will total KSh 1,000-2,500. This is where it starts to feel real. A KSh 2,000 month of passive income is the equivalent of a part-time income stream that requires zero ongoing work.
Year 3-5: Substantial
KSh 2,500-5,000 per month from investments. This is a material supplement to a Kenyan salary — enough to cover a month's transport and groceries, or enough to add meaningfully to next month's investment. The compounding is accelerating visibly.
📊 THE NUMBERS: The average Kenyan who starts investing KSh 5,000/month at age 25 and stays consistent until age 35 will have built a portfolio generating approximately KSh 5,000-8,000 per month in passive income without any salary above the median, without any high-risk investment, and without any dramatic financial event. The only inputs required are time and consistency.
Making Cents of It
The proverb is 'take care of the pennies and the pounds will take care of themselves.' In Kenya, take care of the five thousands and the millions will take care of themselves.
KSh 5,000 is not a lot of money on its own. KSh 5,000 invested consistently, reinvested completely, and guided by AI tools that help you make better decisions than you would make alone, that is the beginning of something that looks very different after five years.
The income stream does not arrive dramatically. It grows one percentage point at a time, one maturity at a time, one dividend season at a time, until one month you open your portfolio tracker and realise your investments are generating more than your salary contributes.
That month is worth every single boring, consistent, unsexy contribution that preceded it.
What would you do with an extra KSh 2,000 per month from investments? Share in the comments.
📖 RELATED READING: From Zero to KSh 1 Million: The AI-Powered Portfolio Strategy That Changed My Financial Story at 32 the full five-year story of building a diversified Kenyan investment portfolio on a normal salary.
📖 RELATED READING: Money Market Funds in Kenya: The Complete 2026 Guide - the best starting vehicle for KSh 5,000/month investors, with a full comparison of providers and step-by-step account opening instructions.
Disclaimer
This article is published by The Net Worth Shift for educational and informational purposes only. All financial projections, return figures, and portfolio values cited are illustrative examples based on reasonable historical assumptions — they are not guarantees of any specific outcome. Actual investment returns vary based on market conditions, fund performance, and individual circumstances. Nothing in this article constitutes personalised financial advice. Investment involves risk including possible loss of principal. Money market fund returns fluctuate with Kenya's interest rate environment. Affiliate income projections are highly variable and are not guaranteed. Consult a professional licensed by Kenya's Capital Markets Authority (CMA) at cma.or.ke before making significant investment decisions.