Don't Bank On It: 5 Investing Mistakes Every Kenyan Under 35 Makes (And How AI Helps You Fix Each One)
: investing mistakes Kenyan common investing mistakes Kenya, how to start investing Kenya young, AI investing tips Kenya, money mistakes Kenya 20s 30s
Let me tell you about the KSh 47,000 I didn't earn.
That is my rough estimate of how much extra my money would have grown between age 22 and age 28 if I had put it in the right places instead of a savings account earning 4% while inflation ran at 7%.
I didn't lose it dramatically. No bad stock pick, no scam, no financial crisis. I just didn't know better and nobody told me. I banked on the idea that saving was enough. It wasn't.
If you are under 35 in Kenya right now, this post is for you. Not because you are doing everything wrong but because the five mistakes below are so common among young Kenyan professionals that they are practically a rite of passage. The difference is that you now have something I didn't have at 22: free AI tools that can help you calculate the cost of each mistake and build a personalised plan to fix it.
📊 THE MATHS: A 25-year-old Kenyan who invests KSh 5,000 per month in a money market fund returning 12% annually will have approximately KSh 1.76 million by age 35. The same person who waits until 30 to start will have approximately KSh 820,000 by 35. The cost of waiting five years: KSh 940,000. No risk. No stock picking. Just time.
The 5 Mistakes at a Glance

| Mistake | What most Kenyans do | What to do instead | Annual cost of mistake |
| Banking all savings | Leave everything in savings account at 4% | Split: MMF (liquid) + T-bills (growth) | KSh 8,000–15,000 lost to inflation per KSh 100K |
| Ignoring M-Pesa loan costs | Roll over Fuliza / M-Shwari regularly | Calculate true annual cost, clear first | 300–400% effective annual rate on daily-fee loans |
| Waiting to invest | 'I'll start when I earn more' | Start with KSh 1,000 today in a MMF | 10 years of compounding lost — irretrievable |
| One stock, one sector | Put everything into Safaricom shares | Spread across 3+ sectors as portfolio grows | Single company risk — one bad year wipes gains |
| No investment plan | React to tips and guesswork | AI-built personalised plan, reviewed monthly | Inconsistent returns, no compounding momentum |
Now let us go through each one in detail with the real cost, a real fix, and an AI prompt that does the heavy lifting for you.
The 5 Mistakes
🏦 MISTAKE #1
Trusting Your Savings Account to Build Wealth
The most expensive mistake that feels the safest
💸 WHAT IT COSTS YOU: KSh 3,000 - 7,000 per KSh 100,000 per year, silently, in purchasing power lost to inflation
Your savings account is not saving you. It is shrinking you slowly, politely, and without sending a single notification. At 4% interest and 7% inflation, every KSh 100,000 you keep in a standard bank savings account loses approximately KSh 3,000 in real purchasing power every year. Over five years, that is KSh 15,000 gone from a balance that still shows a growing number. The cruelty is that you feel responsible the entire time.
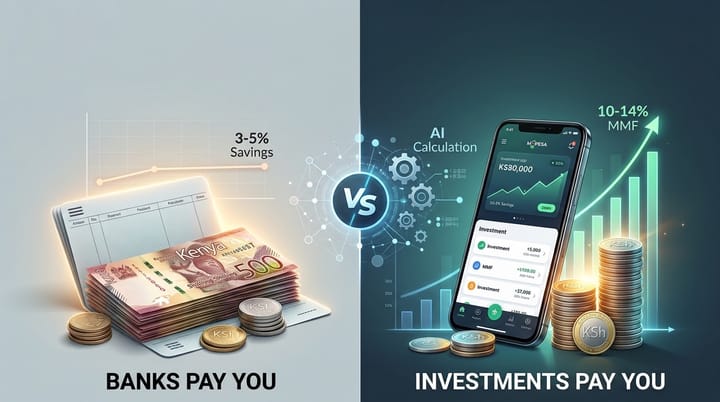
The fix is not complicated, first keep one to three months of expenses in your savings account for genuine emergencies. Move everything above that into a money market fund such as CIC, Sanlam, or NCBA are good starting points, currently returning 10-14% annually. That difference of 6-10 percentage points is not a rounding error. On KSh 200,000, it is the difference between earning KSh 8,000 and earning KSh 20,000 in a year. For a full guide to Kenyan money market funds including how to open an account in 20 minutes, see: Money Market Funds in Kenya: The Complete 2026 Guide.
🤖 AI FIX - paste this into ChatGPT:
"I currently have KSh [amount] in a bank savings account earning approximately 4% interest annually. Inflation in Kenya is running at approximately 7%. Calculate: what is my real return? How much purchasing power am I losing each year? If I moved this money to a money market fund returning 12%, how much more would I earn over 1, 3, and 5 years? Show me the numbers."
✅ THE FIX IN ONE LINE: Move everything above your 1-month emergency buffer from your savings account to a money market fund this week.
📱 MISTAKE #2
Not Knowing the True Cost of Mobile Loans
Fuliza, M-Shwari, and the 300% annual rate hiding in plain sight
💸 WHAT IT COSTS YOU: Potentially hundreds of thousands of shillings in interest over a working career being paid in small daily amounts that feel harmless
Fuliza charges 1.083% per day on the outstanding balance. That sounds tiny. It is not. Annualised, 1.083% per day works out to approximately 395% effective annual rate which is more than twenty times what a bank loan costs. Most Kenyans who use Fuliza regularly are not aware of this number because Safaricom presents it as a daily fee rather than an annual rate. The same applies to many digital lending apps that advertise low daily or weekly rates that mask extraordinary annual costs.
This is not a lecture about avoiding mobile loans entirely. Sometimes Fuliza saves your week and that is fine. The mistake is rolling it over repeatedly without a plan to clear it or using it to cover lifestyle expenses rather than genuine emergencies. Before your next investment, calculate exactly what your mobile loan products are costing you annually. If any of them exceed 20% annual interest, clearing that debt is your highest-returning investment available because it removes a guaranteed cost.
🤖 AI FIX - paste this into ChatGPT:
"I use the following borrowing products in Kenya: [list each one with the daily/weekly/monthly fee and typical balance you carry]. Please calculate the effective annual interest rate for each one. Compare these rates to the return on a money market fund at 12% annually. Tell me in which order I should prioritise clearing these debts, and how long it will take if I put KSh [your available surplus] per month toward them."
✅ THE FIX IN ONE LINE: Calculate the annual rate on every borrowing product you use, then clear the most expensive one before investing a single additional shilling.
⏰ MISTAKE #3
Waiting Until You Earn More to Start Investing
'I'll start properly when I'm earning KSh 100K per month'
💸 WHAT IT COSTS YOU: Every year of delay at age 22-30 costs more in lost compounding than any amount of extra income can recover in your 30s
This is the most emotionally convincing mistake on this list because it feels responsible. Waiting until you are more financially stable before investing sounds like prudence. It is actually the most expensive form of procrastination available. Compound interest rewards time above everything else. KSh 2,000 per month invested from age 24 will grow more by age 45 than KSh 10,000 per month invested from age 34, even though the later investor puts in far more money. The maths is not close. The early investor wins, almost without exception, because of the extra decade of compounding.
The fix is simple and uncomfortable: start now with what you have, not later with what you hope to have. Kenya's money market funds accept as little as KSh 1,000. Ziidi Trader allows you to buy NSE shares from 1 share. The amount matters less than the habit and the habit matters less than the time. Every month you delay is a month of compounding you can never recover. Open one account this week. Put in KSh 1,000 if that is all you have. The account being active is the most important first step.
🤖 AI FIX - paste this into ChatGPT:
"I am [your age] years old living in Kenya, earning KSh [your salary] per month. I have been telling myself I will start investing when I earn more. Please show me: if I start investing KSh [small amount you can actually afford now] per month today versus waiting 2 more years to invest KSh [larger amount], which strategy produces more wealth by age 45? Show me the numbers and tell me honestly whether waiting is a good financial decision."
✅ THE FIX IN ONE LINE: Open one investment account today even with KSh 1,000. The account being active matters more than the amount.
🎯 MISTAKE #4
Putting All Your Investment Money in One Place
The concentration trap - when comfort becomes a liability
💸 WHAT IT COSTS YOU: One bad earnings report, one regulatory change, or one sector downturn can wipe years of gains from a concentrated portfolio
Safaricom is a remarkable company. It dominates telecommunications, runs the world's most sophisticated mobile money platform, and has created enormous shareholder value since listing on the NSE. It is also the one stock that most Kenyan beginners buy — and the one stock they put most of their portfolio into, because it is familiar and feels safe. Familiarity is not diversification. A portfolio that is 80% Safaricom is 80% exposed to the risks of one company, one sector, and one regulatory environment. Even excellent companies have bad years.
Diversification does not mean owning twenty stocks. For a beginner, it means spreading your investment across at least two to three different types of instruments — for example, a money market fund for liquidity, treasury bills for safe fixed returns, and NSE stocks across at least two different sectors. Within your stock allocation, owning three companies in different sectors (banking, telecoms, consumer goods) dramatically reduces the risk that one company's bad year destroys your portfolio's growth.
🤖 AI FIX - paste this into ChatGPT:
"I currently have all my investment money in [one stock / one fund / one type of investment]. Please explain the concept of diversification and why concentration in one investment is risky. Then suggest a framework for how I might spread KSh [your investment amount] across different investment types available in Kenya in 2026, based on my age of [your age] and a medium risk tolerance. I want to understand the reasoning, not just the answer."
✅ THE FIX IN ONE LINE: Spread your money across at least two different investment types — ideally across different sectors and instruments.
🗺️ MISTAKE #5
Investing Without a Written Plan
The difference between investing and gambling is a plan
💸 WHAT IT COSTS YOU: Inconsistent contributions, emotionally-driven decisions, no progress tracking and no way to know if you are winning or losing
Most Kenyans who invest do so reactively by buying when they feel confident, selling when they feel worried, contributing when they remember to, stopping when expenses get tight. This is not investing. It is financial improvisation, and it produces improvised results. The investors who consistently build wealth across all income levels almost always share one thing: they have a written plan that specifies how much they invest, in what, and why. The plan does not need to be complex. It needs to exist and to be reviewed regularly.
A good personal investment plan covers five things: your monthly investment amount (a fixed number, not 'whatever is left over'), where that money goes (specific funds or accounts), your target amount and timeline, how you will handle months when money is tight, and when you will review the plan. Writing it down in a Notes app on your phone makes it 3× more likely to happen, according to research on goal-setting. Using an AI tool to build and review your plan means it adapts as your situation changes.
🤖 AI FIX - paste this into ChatGPT:
"I am a [your age]-year-old Kenyan professional earning KSh [your salary] per month. I want to create a simple, written personal investment plan. Please help me build one that covers: my monthly investment amount (I can realistically invest KSh [amount] per month), where to invest it across Kenyan options available in 2026, my 3-year and 5-year financial goals in specific KSh amounts, what I should do in months where money is tighter than usual, and how to review the plan every quarter. Make it simple enough that I will actually follow it."
✅ THE FIX IN ONE LINE: Write your investment plan down even in your phone's Notes app. A plan that exists beats a perfect plan that doesn't.
Which of These Mistakes Is Costing You the Most?
Use this prompt to find out exactly which mistake is having the biggest financial impact on your specific situation:
"I am a Kenyan professional aged [your age] earning KSh [your salary] per month. Here is my current financial situation: [briefly describe — savings account balance, any mobile loans, when you started investing, what you are invested in, whether you have a plan]. Based on this, which of the following mistakes is currently costing me the most money: keeping too much in a savings account, high-interest mobile loans, having delayed starting to invest, being too concentrated in one investment, or not having a written plan? Calculate the approximate annual cost of my biggest mistake and tell me what to fix first."
The AI will prioritise based on your real numbers giving you a personalised answer rather than a generic one.

The Honest Truth About These Mistakes
Every single person who is now financially secure in their 40s made at least two or three of these mistakes in their 20s and 30s. These are not signs of failure. They are signs of not having been taught what nobody teaches us in school.
The difference between the people who build wealth and the people who wish they had is rarely intelligence or income. It is information applied at the right time. You now have that information.
The AI tools available in 2026 mean that the fix for every single mistake on this list is available to you for free, right now, on your phone. The only thing that remains is whether you use it.
Share this with a friend who needs to read it.
📖 RELATED READING: 7 Free AI Tools for Investing in Kenya in 2026 the exact tools to use for each of the five fixes above, with ready-to-use prompts for each one.
Disclaimer
This article is published by The Net Worth Shift for educational purposes only. Nothing here constitutes personalised financial advice. The financial projections and examples used are illustrative , actual returns depend on market conditions, fund performance, and individual circumstances. AI tools can produce inaccurate information, always verify specific rates and product details directly with providers. Investment involves risk including possible loss of principal. Consult a professional licensed by Kenya's Capital Markets Authority (CMA) at cma.or.ke before making significant investment decisions.